Skip to content
Official PYQ · 2017

GATE EC 2017 Set 1 Q51 — Random Processes

Explain with AI

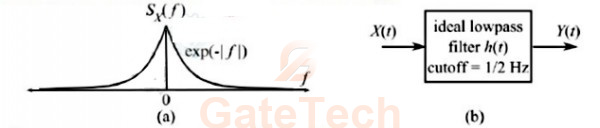
Let X(t)X(t) be a wide sense stationary random process with the power spectral density SX(f)S_{X}(f) as shown in Figure (a), where ff is in Hertz(Hz)(Hz). The random process X(t)X(t) is input to an ideal lowpass filter with the frequency response

H(f)={1,∣f∣≤12Hz0,∣f∣>12HzH(f) = \begin{cases} 1, & \mid f \mid \leq \frac{1}{2} Hz \\ 0, &\mid f \mid > \frac{1}{2} Hz \end{cases}

as shown in Figure(b).The output of the lowpass filter is Y(t)Y(t).

Let EE be the expectation operator and consider the following statement:

  1. E(X(t))=E(Y(t))E(X(t))=E(Y(t))
  2. E(X2(t))=E(Y2(t))E(X^{2}(t))=E(Y^{2}(t))
  3. E(Y2(t))=2E(Y^{2}(t))=2

Select the correct option:

Choose one option
View answer

Answer: A

Worked explanation not available yet.

Free practice · Your answers on this page are not saved.

Published
Report a correction
Keep exploringMore Random Processes questions